
New York City had eleven deals and more than $5.8 billion in disclosed volume last week, and the active commercial lenders doing those deals weren’t all playing the same game. Eight were CRE deals: a $3.3 billion construction loan, a $750 million multifamily refinancing, and six others from $24 million to $143 million. Two were growth capital deals. One was an ABL factoring line. The city pulled capital from every vertical in the bracket.
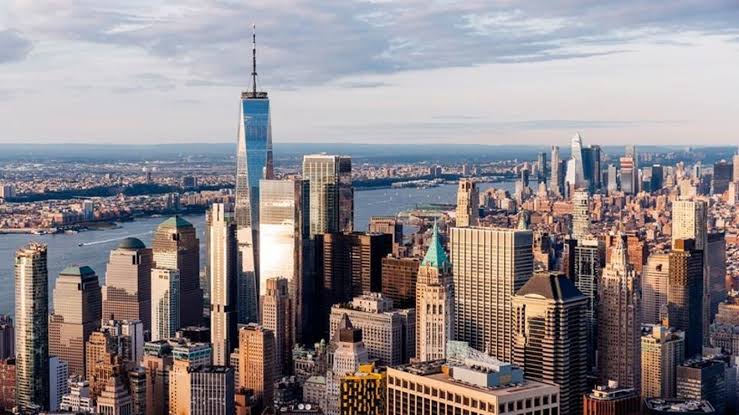
The NYC Mix Last Week
The $3.3 billion 350 Park Avenue construction loan for the JPMorgan co-lead with Wells Fargo is the anchor. That deal alone is larger than the entire disclosed CRE volume of every other city combined.
But strip that one deal out and New York still had ten other closings worth $2.5 billion. The Manhattan Plaza refinancing at $750 million is the next largest. Then a $143 million multifamily construction loan in Brooklyn, a $95 million multifamily deal at 544 Carroll Street (KKR, 10-year fixed), and four more ranging from $24 million to $52.5 million.
The growth capital side is easy to miss because it doesn’t show up in a CRE headline. JPMorgan Chase co-led the $750 million Watsco revolving credit. The Watsco headquarters is in Coconut Creek, Florida, but the deal was arranged out of New York, and the lead arrangers are New York institutions. Fundfi closed an undisclosed facility for a Flatiron District company. Two more GC deals, both New York shops.
The ABL deal is a factoring line, also undisclosed in amount, for an unnamed borrower. Small, but present.
Which Active Commercial Lenders Closed NYC Deals?
| Lender | Deal | Amount | Structure | Vertical |
|---|---|---|---|---|
| JPMorgan Chase + Wells Fargo (co-leads) | 350 Park Ave construction | $3.3B | Construction loan | CRE |
| Undisclosed | Manhattan Plaza refinance | $750M | Refinance | CRE |
| JPMorgan Chase + multiple (joint leads) | Watsco revolving credit | $750M | Revolving credit | GC |
| KKR Real Estate Finance | 544 Carroll St, Brooklyn | $95M | 10-year fixed | CRE |
| S3 Capital | 1527 York Ave, Upper East Side | $52.5M | Construction | CRE |
| ICBC | 511 Fifth Ave | $45.5M | Undisclosed | CRE |
| Undisclosed | LIC condo | $36.2M | Undisclosed | CRE |
| ICBC | 148 Madison Ave | $24.4M | Undisclosed | CRE |
| Undisclosed (441-467 Prospect, Brooklyn) | Brooklyn multifamily construction | $143M | Construction | CRE |
| Fundfi | Flatiron District (undisclosed) | Undisclosed | GC facility | GC |
| Undisclosed | ABL factoring | Undisclosed | Factoring | ABL |
Why NYC and Why Not the Runner-Up
The runner-up was Dallas-Fort Worth at three deals and roughly $190 million. Look, that is a real market. But it is not in the same conversation as eleven deals and $5.8 billion.
What keeps New York at the top is not just the trophy construction deals. It is the density. You can put a $3.3 billion construction loan, a $52.5 million condo construction deal, a $750 million national revolving credit, and a factoring line into the same MSA in the same week without any of them competing for the same lender relationships. That depth of capital supply doesn’t exist in many markets.
The Upper East Side deal is a good example of how specific that market is.
“Upper East Side condo buyers are a specific audience, and a 28-unit building with layouts up to five bedrooms is aimed squarely at them.” Shawn Safdie, Head of Origination, S3 Capital
S3 Capital gets that specificity right. The deal closed because the lender understood the sub-market, not because Manhattan is generally a good place to build condos.
Where Capital Is Concentrating by Vertical
🏢 CRE: Construction and refinancing in equal measure. Eight CRE deals. Four were construction or bridge financings. Four were permanent or refinance structures. The borough split: Manhattan dominated on volume ($3.3B, $750M, $52.5M, $45.5M, $24.4M). Brooklyn had the $143M and $95M multifamily deals. Long Island City had the $36.2 million condo.
🚀 GC: Two deals, both undisclosed amounts except the Watsco revolving credit at $750M. Active commercial lenders in growth capital are placing lead arranger roles in New York even when the borrower is headquartered elsewhere.
⚙️ ABL: One factoring deal, undisclosed amount. The ABL market in New York tends to show up in deal count more than in volume, because the large dollar ABL facilities often anchor in regional banking centers.
International Cities
The international deal pool last week was anchored in Australia (Akaysha Energy BESS, $1.248 billion CRE), Lithuania ($126.9 million GC), Colombia ($70 million GC), and Thailand ($60 million GC). No single international city matched NYC’s deal count, but South Australia had the largest single deal in the entire package outside the US.
What to Do
If you are a CRE borrower in New York: Construction lending is active at the top and in the middle of the market simultaneously. A $3.3 billion construction loan and a $52.5 million condo construction loan closed in the same week, from lenders at opposite ends of the balance sheet. If you have a shovel-ready project and a real equity stack, the capital is available.
If you are an active commercial lender not currently closing deals in New York: The MSA concentration data is telling you something. Eleven deals in one week means there are active borrower relationships, active broker relationships, and active deal flow. The question is whether you can underwrite the asset types that are closing there.
Keep reading:
Top Industrial
Frauds and Bankruptcies
Lender of the Week
ABL Niche Focus
Market Signals
Commercial Real Estate Lender Rankings
Growth Capital Lender Rankings
Asset-Based Lender Rankings